

Ranked: Top U.S. Industries by Investment Share (1949–2025)

 See more visuals like this on the Voronoi app.

Save to Inbox
Ranked: Top U.S. Industries by Investment Share (1949–2025)
See visuals like this from many other data creators on our Voronoi app. Download it for free on iOS or Android and discover incredible data-driven charts from a variety of trusted sources.
Key Takeaways
- The industries attracting the most investment in the U.S. have shifted dramatically over time, from farming and railroads to technology and data.
- Today’s leading sector, information and data processing, commands a smaller share of total investment than past dominant industries.
Investment has long been a driving force behind U.S. economic growth, but the sectors attracting the most capital have changed with each era. From agriculture and electrification in the mid-20th century to telecommunications, real estate, and now digital infrastructure, investment trends reflect broader shifts in technology, consumer demand, and policy.
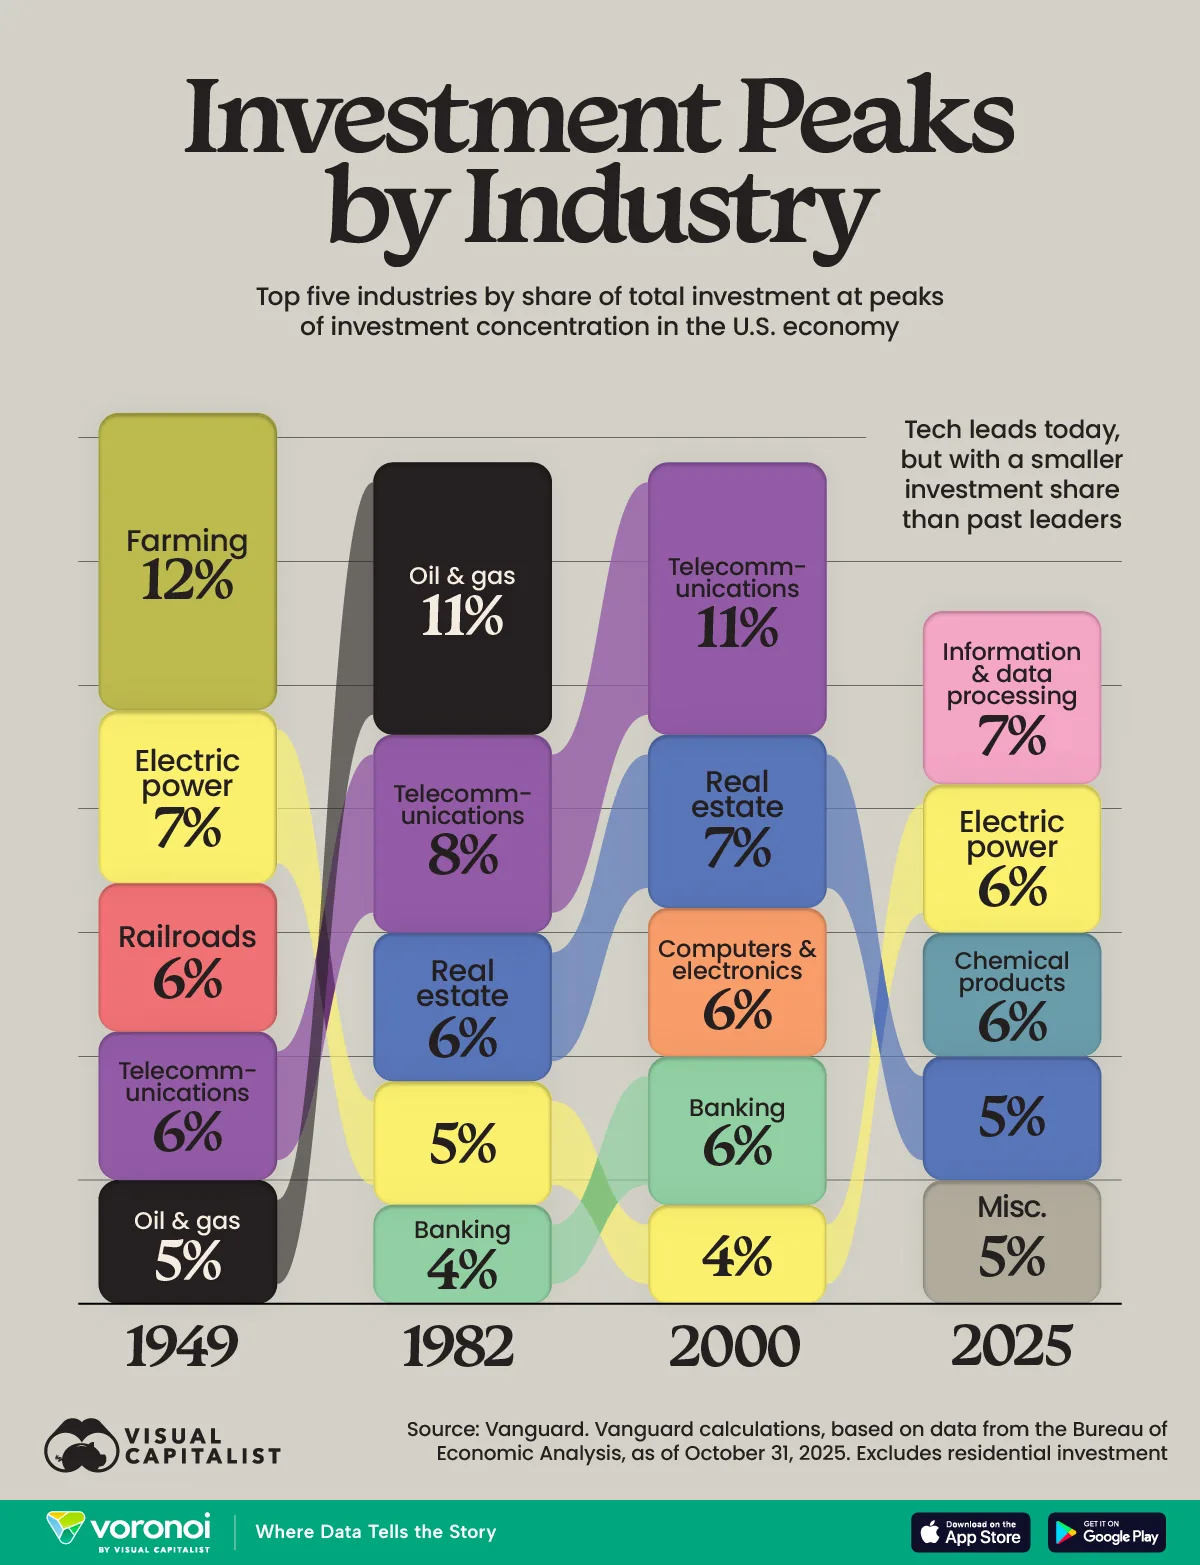
This visualization shows the top five U.S. industries by share of total investment at key historical peaks, spanning 1949 to 2025. The data for this visualization comes from Vanguard, using calculations based on Bureau of Economic Analysis data as of October 31, 2025. The figures exclude residential investment.
Postwar America: Farming, Power, and Railroads
In 1949, U.S. investment was concentrated in industries that supported a rapidly expanding, industrializing economy.
Farming led with a 12% share of total investment, reflecting the sector’s central role in employment and production. Electric power and railroads followed closely, underscoring the importance of nationwide infrastructure as the U.S. rebuilt and modernized after World War II. Telecommunications and oil and gas rounded out the top five.
| Era | Rank | Industry | Share |
|---|---|---|---|
| 1949 | 1 | Farming | 12% |
| 2 | Electric power | 7% | |
| 3 | Railroads | 6% | |
| 4 | Telecommunications | 6% | |
| 5 | Oil and gas | 5% | |
| 1982 | 1 | Oil and gas | 11% |
| 2 | Telecommunications | 8% | |
| 3 | Real estate | 6% | |
| 4 | Electric power | 5% | |
| 5 | Banking | 4% | |
| 2000 | 1 | Telecommunications | 11% |
| 2 | Real estate | 7% | |
| 3 | Computers and electronics | 6% | |
| 4 | Banking | 6% | |
| 5 | Electric power | 4% | |
| 2025 | 1 | Information and data processing | 7% |
| 2 | Electric power | 6% | |
| 3 | Chemical products | 5% | |
| 4 | Real estate | 5% | |
| 5 | Miscellaneous | 5% |
The 1980s and 2000s: Energy, Communication, and Finance
By 1982, investment leadership had shifted toward oil and gas, which accounted for 11% of total investment. Telecommunications and real estate also gained prominence, alongside banking and electric power.
In 2000, at the height of the dot-com era, telecommunications topped the list, while computers and electronics emerged as a major investment destination. Real estate and banking also featured prominently.
2025: Technology Dominates, but Less Concentrated
Today, information and data processing leads U.S. investment with a 7% share—making it the top industry, but with far less dominance than historical leaders. Electric power, chemical products, and real estate follow closely, each capturing around 5–6% of total investment.
This lower concentration suggests a more diversified investment landscape, where capital is spread across a wider range of industries rather than clustered in a single dominant sector.
Learn More on the Voronoi App
If you enjoyed today’s post, check out America’s $38 Trillion Mountain of Debt on Voronoi, the new app from Visual Capitalist.


The Global Stock Market Boom, by Country (2011–2025)
Global equities more than tripled in total market capitalization between 2011 and 2025. One country’s stocks powered most of this growth.


How the Global Stock Market Boom Unfolded
Key Takeaways
- Global equity markets rose by more than $100 trillion in value between 2011 and 2025.
- The U.S. led this growth, rising from $15.6 trillion in 2011 to $68.9 trillion in 2025.
- China surpassed Japan in 2014 and, by 2025, matched the European Union at $15.5 trillion.
Over the past 15 years, the balance of global equity market value has shifted substantially as some markets expanded much faster than others.
This visualization tracks equity market capitalization from 2011 to 2025, using World Federation of Exchanges figures published in SIFMA’s Capital Markets Fact Book.
Market capitalization measures the value of outstanding shares at prevailing prices; all figures are expressed in nominal U.S. dollars and are not adjusted for inflation.
The Changing Leaderboard of Equity Markets
The U.S. has pulled comfortably ahead, expanding from $15.6 trillion in 2011 to $68.9 trillion of market capitalization in 2025. Its share of the global total grew from less than a third to roughly 44%.
Below the leader, the order shifted. China’s equity market surpassed Japan’s in 2014 amid a surge in stock buying, while India overtook Japan in 2021. By 2025, China and the European Union were level at approximately $15.5 trillion each.
The table below lists the world’s largest equity markets in both 2011 and 2025.
| Equity Market | Market capitalization ($T) | |
|---|---|---|
| 2011 | 2025 | |
| 🇺🇸 U.S. | 15.6 | 68.9 |
| 🇨🇳 China | 3.4 | 15.5 |
| 🇪🇺 European Union | 6.0 | 15.5 |
| 🇮🇳 India | 2.0 | 10.6 |
| 🇯🇵 Japan | 3.5 | 7.6 |
| 🇭🇰 Hong Kong | 2.3 | 6.1 |
| 🇬🇧 United Kingdom | 3.3 | 5.6 |
| 🇨🇦 Canada | 1.9 | 4.6 |
| 🇦🇺 Australia | 1.2 | 2.0 |
| Other developed markets | 4.4 | 14.4 |
| Other emerging markets | 6.0 | 6.9 |
| Global total | 49.6 | 157.8 |
The trend of a rising U.S. share of global equity markets reversed in 2025. While U.S. market capitalization continued to grow, its share of the global total fell from roughly 47% in 2024 to 44% in 2025 as markets elsewhere grew faster.
The U.S. nevertheless remains home to the New York Stock Exchange and Nasdaq, the world’s two largest stock exchanges.
How Tech Giants Expanded America’s Lead
The rise of large technology companies helps explain the U.S. market’s growing weight. Businesses built around software, digital advertising, and cloud computing can serve customers worldwide, allowing their revenue to expand far beyond the U.S. economy.
More recently, artificial intelligence has added another source of investor enthusiasm. Advances in AI and subsequent investor interest have boosted valuations for a subset of technology firms. Expectations of future profits can lift share prices well before those profits arrive, with substantial effects on the broader market.
Specifically, the so-called Magnificent Seven stocks have accounted for most of the S&P 500’s total return in both 2024 and 2025. This group consists of Alphabet, Amazon, Apple, Meta, Microsoft, NVIDIA, and Tesla.
The Gap Between Market Size and Economic Size
A stock market measures the value investors place on listed businesses rather than everything an economy produces. Private companies are absent, while listed multinationals can earn substantial revenue abroad.
China’s mid-2010s boom shows how financial conditions can reshape valuations. Heavy buying with borrowed money helped fuel the 2015 rally before prices reversed sharply that summer. Borrowing can amplify purchasing power on the way up and increase pressure to sell when prices fall.
The following table shows how the market capitalization of leading equity markets changed between 2011 and 2025.
| Year | Equity Market Cap ($T) | |||||||
|---|---|---|---|---|---|---|---|---|
| Australia | Canada | China | EU | India | Japan | UK | U.S. | |
| 2011 | 1.2 | 1.9 | 3.4 | 6.0 | 2.0 | 3.5 | 3.3 | 15.6 |
| 2012 | 1.4 | 2.1 | 3.7 | 6.9 | 2.5 | 3.7 | 3.4 | 18.7 |
| 2013 | 1.4 | 2.1 | 3.9 | 8.6 | 2.3 | 4.5 | 4.4 | 24.0 |
| 2014 | 1.3 | 2.1 | 6.0 | 7.9 | 3.1 | 4.4 | 4.0 | 26.3 |
| 2015 | 1.2 | 1.6 | 8.2 | 7.6 | 3.0 | 4.9 | 3.9 | 25.1 |
| 2016 | 1.3 | 2.0 | 7.3 | 7.7 | 3.1 | 5.1 | 3.5 | 27.4 |
| 2017 | 1.5 | 2.4 | 8.7 | 9.8 | 4.7 | 6.2 | 4.5 | 32.1 |
| 2018 | 1.3 | 1.9 | 6.3 | 8.1 | 4.1 | 5.3 | 3.6 | 30.4 |
| 2019 | 1.5 | 2.4 | 8.6 | 9.7 | 4.3 | 6.2 | 4.2 | 34.1 |
| 2020 | 1.7 | 2.6 | 12.3 | 11.1 | 5.1 | 6.7 | 4.0 | 41.6 |
| 2021 | 1.9 | 3.3 | 14.4 | 13.8 | 7.1 | 6.5 | 3.8 | 48.5 |
| 2022 | 1.7 | 2.8 | 11.5 | 11.0 | 6.8 | 5.4 | 3.1 | 40.3 |
| 2023 | 1.8 | 3.1 | 10.9 | 12.6 | 8.7 | 6.1 | 4.5 | 49.0 |
| 2024 | 1.7 | 3.4 | 11.6 | 11.1 | 10.3 | 6.3 | 4.4 | 62.2 |
| 2025 | 2.0 | 4.6 | 15.5 | 15.5 | 10.6 | 7.6 | 5.6 | 68.9 |
Learn More on the Voronoi App
To explore the stocks that have powered U.S. market growth, check out The 10 Largest S&P 500 Stocks in 2025 on Voronoi.
Ranked: Profit Margins of the World’s Largest Companies
Nvidia keeps nearly $56 of every $100 in revenue as profit. For some of the world’s largest companies, it’s less than $1.


How Much Profit Do the World’s Biggest Companies Keep?
Key Takeaways
- Nvidia generates $55.60 in profit for every $100 in revenue, the highest margin among the Fortune Global 500’s 30 largest companies.
- Big Tech dominates the top of the ranking, with Microsoft, Alphabet, and Meta each keeping more than $30 of every $100 in revenue as profit.
- At the other end, several of the world’s largest retailers, health care companies, and energy firms keep less than $5 per $100.
The world’s biggest companies generate enormous revenues, but the share that ultimately becomes profit varies widely.
This graphic ranks the world’s 30 largest companies by how much profit they generate for every $100 in revenue, based on Fortune Global 500 data. Profits are after taxes, extraordinary credits or charges, accounting changes, and noncontrolling interests, but before preferred dividends.
Why Tech Keeps More of Every $100
Revenue measures how much money flows through a company, but not how much ultimately reaches the bottom line. Across the world’s largest companies, Big Tech stands apart in how much of that revenue becomes profit.
| Rank | Name | Profit per $100 in Revenue (2026) | Profit |
|---|---|---|---|
| 1 | Nvidia | $55.60 | $120B |
| 2 | Microsoft | $36.10 | $102B |
| 3 | Alphabet | $32.80 | $132B |
| 4 | Meta | $30.10 | $60B |
| 5 | Apple | $26.90 | $112B |
| 6 | Industrial & Commercial Bank of China | $24.30 | $51B |
| 7 | Saudi Aramco | $20.80 | $93B |
| 8 | JPMorgan Chase | $20.30 | $57B |
| 9 | Berkshire Hathaway | $18.00 | $67B |
| 10 | Samsung Electronics | $13.30 | $31B |
| 11 | Amazon | $10.80 | $78B |
| 12 | ExxonMobil Holdings | $8.70 | $29B |
| 13 | Toyota Motor | $7.60 | $26B |
| 14 | Shell | $6.50 | $18B |
| 15 | China National Petroleum | $5.30 | $21B |
| 16 | Walmart | $3.10 | $22B |
| 17 | Costco Wholesale | $2.90 | $8B |
| 18 | UnitedHealth Group | $2.70 | $12B |
| 19 | Hon Hai Precision Industry | $2.30 | $6B |
| 20 | Volkswagen | $2.30 | $8B |
| 21 | Cigna Group | $2.20 | $6B |
| 22 | State Grid | $2.00 | $11B |
| 23 | Sinopec Group | $1.40 | $5B |
| 24 | McKesson | $1.20 | $5B |
| 25 | Trafigura Group | $1.10 | $3B |
| 26 | China State Construction Engineering | $1.10 | $3B |
| 27 | Cardinal Health | $0.70 | $2B |
| 28 | Cencora | $0.50 | $2B |
| 29 | CVS Health | $0.40 | $2B |
| 30 | Glencore | $0.10 | $0.4B |
Profits rounded to the nearest 10 cents.
The gap is striking even among corporate giants. Microsoft generates $36.10 in profit for every $100 in revenue, compared with roughly $3 for Walmart and Costco. Enormous revenue does not necessarily translate into an equally large profit margin.
Much of the difference comes down to business models. Software and digital platforms can serve additional customers at relatively low incremental cost, while retailers, manufacturers, and energy companies must continually pay for inventory, labor, raw materials, logistics, or production.
AI Is Rewriting Big Tech’s Business Model
The margins shown above reflect today’s business models, but AI is making many of those models more capital-intensive. Microsoft, Alphabet, Meta, and Amazon are pouring hundreds of billions of dollars into AI infrastructure. Hyperscaler capital spending is on track to reach $785 billion in 2026 and rise to nearly $1 trillion in 2027.
Nvidia is a major beneficiary of this investment. As a dominant supplier of AI chips, it sits at the center of the infrastructure buildout, while its CUDA software ecosystem can make switching to rival chips more difficult for developers.
On the flipside, the scale of AI investment is raising capital costs across Big Tech. As infrastructure spending climbs, those costs could begin to reshape the margins that currently put many tech companies near the top of this ranking.
Learn More on the Voronoi App
To learn more about this topic, check out this graphic on the world’s largest companies outside the U.S.
-

 China2 weeks ago
Ranked: The World’s Best Countries at Math in 2026
-

 population4 weeks ago
Ranked: The Best and Worst Countries to Live In 2026
-

 Debt1 week ago
Ranked: Countries With the Most Government Debt Per Person
-

 Maps4 days ago
Mapped: The Best Employer in Every U.S. State
-

 Housing3 weeks ago
Ranked: 100 Global Cities by Quality of Life and Cost
-

 Brands4 weeks ago
Ranked: Cars That Hold and Lose Their Value the Most
-

 Money3 weeks ago
Ranked: Countries With the Highest Debt-to-GDP Ratios
-

 Economy1 week ago
Ranked: The World’s Strongest City Economies by 2050


